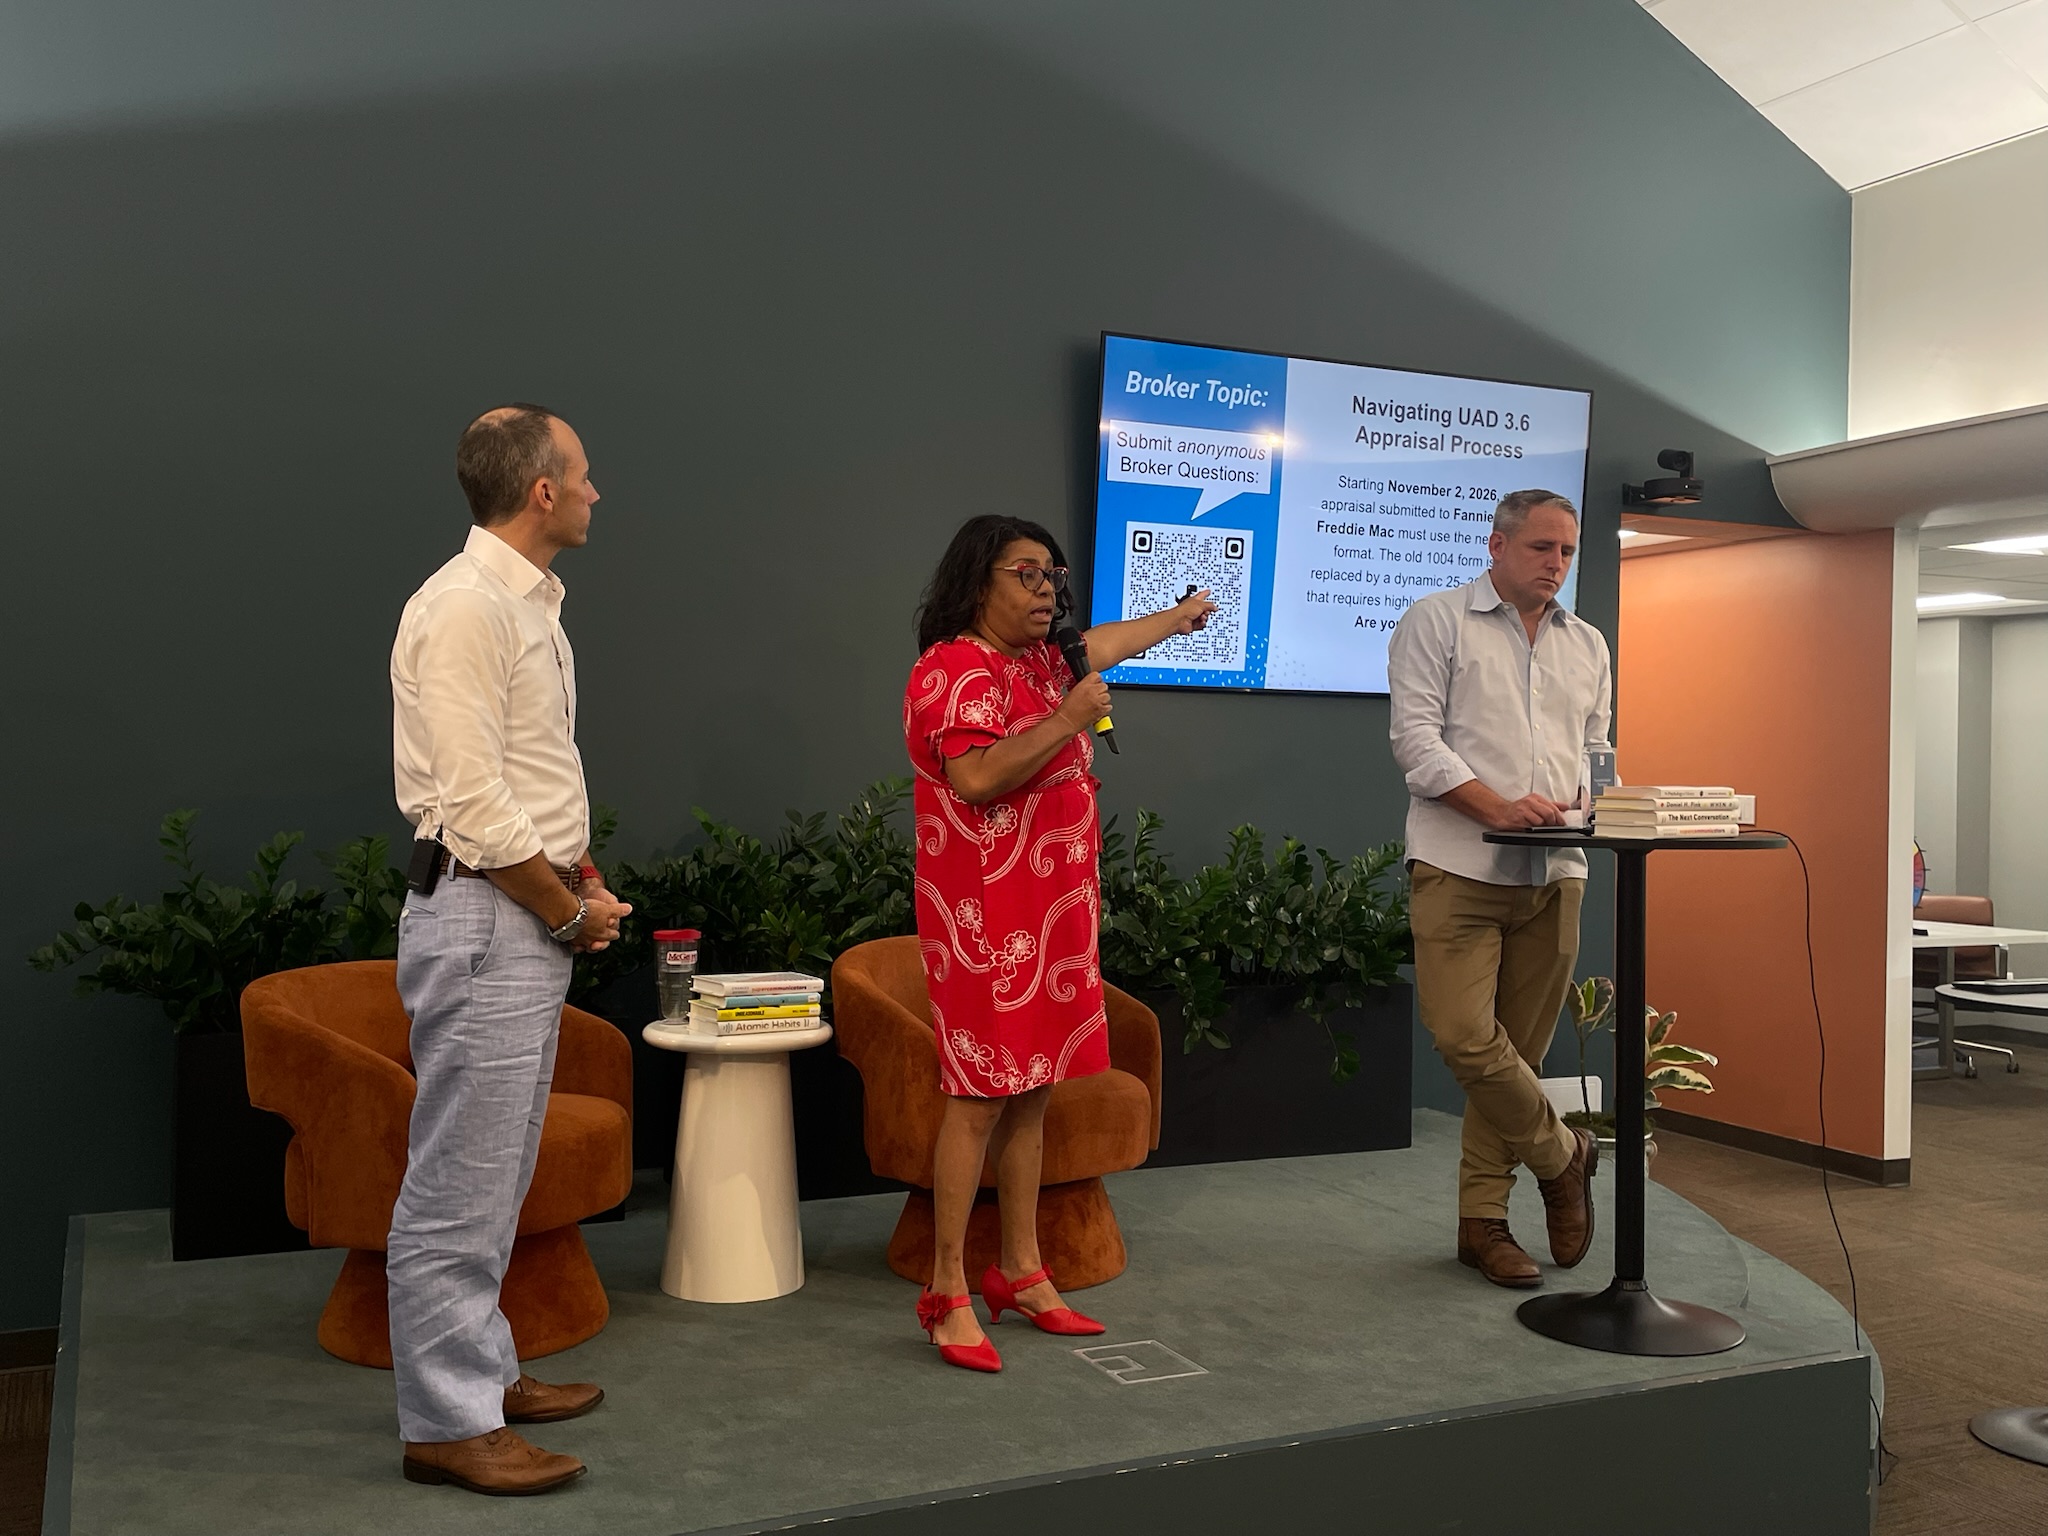
Nichole Donald, Cody Caudill, and Jeffrey Doussan on the FOREWARN check every agent should run before a showing, and on the redesigned appraisal report that Fannie Mae and Freddie Mac make mandatory on November 2, 2026.
Two takeaways for New Orleans agents from this session. First, FOREWARN, the background-check app included with NOMAR membership, lets you check a new prospect’s phone number before you meet them alone. Second, Fannie Mae and Freddie Mac make their redesigned Uniform Residential Appraisal Report (UAD 3.6) mandatory for new appraisals submitted on or after November 2, 2026. The new report asks for more property data, so get listing details together now. FHA is moving to the same format but has not set a mandatory date, and VA had not announced one as of early October 2026.
Why It Matters
Real estate is one of the few professions where you routinely drive alone to an unfamiliar address to meet a stranger. The week of this session, NOMAR emailed members a realtor safety alert, and agents were on edge. At the same time, a redesigned standard appraisal report becomes mandatory for Fannie Mae and Freddie Mac loans on November 2, and listings that aren’t ready for it can slow appraisals down.
At the September 2, 2026 KW New Orleans leadership session, Nichole Donald (Coach and Co-Broker), Cody Caudill (Team Leader), and Jeffrey Doussan (Operating Principal) laid out the practical response to both, focused on what agents can actually do.
The State of Play
Two urgent issues came out of this session: one about personal protection, one about transaction timing. Both reward agents who act early.
If it’s blank when you search them, it should be a red flag, and you should go talk to somebody, right?
Cody Caudill, Team Leader, KW New Orleans
Using FOREWARN: What Agents Should Do Before a Showing
FOREWARN works before the appointment. That is the entire point: once you are already at the property, you have lost the advantage the tool gives you.
The protocol is straightforward: when a new prospect calls asking for a showing or a lease walkthrough, run their number through FOREWARN before you confirm, and run it for every new prospect so everyone gets the same treatment. If the result identifies the caller and raises no concerns, proceed with normal precautions. If it comes back blank (no data at all), Cody’s advice is to treat that as a red flag. If it comes back with a long criminal history, Nichole calls that a red flag too. Either way, talk to your broker or a colleague before you decide how to proceed.
For showings that do move forward, especially when you are going alone, Cody’s advice is to use the KW New Orleans front desk during business hours: give them the property address and the client’s contact information before you leave, and they can check in with you. Outside business hours, send the same information to a trusted colleague or family member who will notice if you don’t check back in. Agents looking to sharpen their overall practice can also explore resources through the KW New Orleans Learning Center.
The Appraisal Overhaul: What Changes on November 2
On November 2, 2026, Fannie Mae and Freddie Mac retire their legacy appraisal forms. Under Fannie Mae’s UAD 3.6 FAQ, every new appraisal report first submitted on or after that date must use the redesigned Uniform Residential Appraisal Report and its data standard, UAD 3.6. A temporary exception announced September 30 lets approved lenders keep submitting the old format through May 19, 2027, but the November 2 date stands for everyone else.
According to the webinar Nichole attended, reports on the new form can run 25 to 30 pages, and appraisers will ask for details that agents and sellers don’t always track, such as the age of the water heater. When that data is missing, the appraiser calls the agent, the agent calls the seller, and the clock keeps running. The cleanest way to get ahead of it is to collect that information at the listing appointment, before a buyer and a deadline are in the picture.
FHA runs on a different clock. In FHA INFO 2026-15 (June 25, 2026), HUD announced that FHA is moving to the same UAD 3.6 report, and HUD’s appraisal portal accepts both the old and new formats until the old one is retired. FHA began accepting the new format on an optional basis on October 1, HousingWire reported, but it has not set a mandatory date. For agents who wanted a deeper dive, KW New Orleans scheduled a four-hour CE course in late September with Rosalyn Bryant of Bryant Appraisal Services on the appraisal changes and the CMA process.
So it’s important for you to start getting your listings ready because it’s going to delay.
Nichole Donald, Coach & Co-Broker, KW New Orleans
The Loan Type Conversation Is Already Happening
Cody’s read is that the appraisal changes are already shaping how some lenders talk to buyers, ahead of the November 2 date.
In his view, some lenders are pushing buyers away from FHA and VA products until they know more, and for some buyers a conventional loan may make sense. Jeffrey pointed out that FHA may still be the best option. Cody didn’t disagree; his point was that agents should know this conversation is already happening. Keep the timing in perspective: conventional loans sold to Fannie Mae and Freddie Mac are the ones with the firm November 2 date, so switching a buyer to conventional financing does not sidestep the new report. The right loan depends on the buyer’s finances and the lender’s advice, and the agent’s job is to have that conversation early and build realistic appraisal time into the contract.
If you have a deal under contract, ask the lender which format the appraisal is being ordered on. Nichole said some lenders are already asking for appraisals on the new format so that a deal caught in the middle of the switchover doesn’t need a second appraisal. For Fannie Mae and Freddie Mac loans, the cutoff is based on when the report is first submitted, so an old-format appraisal that isn’t submitted before November 2 may have to be redone unless the lender has an exception. Buyers looking for available properties can start with the KW New Orleans property search to get a sense of inventory and price points before the financing conversation begins.
Here’s real talk. What I think lenders are doing right now is pushing you away from these products, right? Until they know more, just be aware of that.
Cody Caudill, Team Leader, KW New Orleans
Common Questions
A NOMAR safety alert and a two-hour appraisal webinar landed on Nichole Donald’s desk the same week, and she brought both into the room. The message on safety is simple: FOREWARN is included with NOMAR membership, and a blank search result is a red flag. The message on appraisals is practical: for Fannie Mae and Freddie Mac loans the new report is mandatory starting November 2, so get listing data together and have the loan-type conversation early. Agents who get ahead of both will spend less time explaining delays and more time closing.
About this series. KW New Orleans hosts regular conversations with the leaders shaping our city: developers, architects, investors, and operators building the New Orleans of tomorrow. These are the conversations that happen in the rooms most people don’t get invited into.
KW New Orleans brings together the sharpest minds in real estate, development, and hospitality. If you’re ready to work alongside people building the city’s future, we’d love to talk.