Cody Caudill, Jeffrey Doussan, and Nichole Donald on why high rates shouldn’t automatically sideline first-time buyers, what local NOMAR data says about New Orleans prices, and every deadline agents need for the Matrix-to-Flex MLS switch.
New Orleans real estate keeps telling a different story than the national headlines: NOMAR’s August 2026 report showed the median sale price up 5.2% and the average sale price up nearly 10% year over year, even as high interest rates dominate the national conversation. For agents and buyers here, the question that matters is whether sitting on the sidelines as a renter is actually the safer move. On the operations side, NOMAR’s MLS moves from Matrix to Flexmls on October 26, 2026, and agents can no longer input listings into Matrix starting October 23.
Why It Matters
Every time mortgage rates climb, a familiar story takes over: buyers wait, renters tell themselves it’s not the right time, and the market supposedly freezes. Rates are climbing again: Freddie Mac’s weekly survey put the average 30-year fixed rate at 7.28% on October 1, 2026, up from 7.03% a week earlier. The KW New Orleans leadership team still doesn’t buy the freeze story, and they have the local numbers to push back.
In a September 16, 2026 internal session, Cody Caudill (Team Leader), Jeffrey Doussan (Operating Principal), and Nichole Donald (Coach and Co-Broker) of KW New Orleans worked through two of the most pressing topics facing agents and their clients: the real math behind buying in a high-rate environment, and the operational reality of the October MLS migration from Matrix to Flex that every agent in the market has to work through.
The State of Play
The New Orleans market in late summer 2026 is doing something the national news cycle hasn’t caught up to yet. Here’s what the KW New Orleans leadership team is tracking.
The national news is not our market almost every single time, and that’s what people are hearing, and they’re going to think it’s similar.
Cody Caudill, Team Leader, KW New Orleans
The Rate Math Nobody’s Running for First-Time Buyers
The conversation agents dread most right now is the one where a first-time buyer says rates are too high to act. Doussan’s response cuts through that quickly: compare the actual cost of renting to the actual cost of owning, including what each one builds over time.
The frame he uses is blunt: every dollar a renter pays each month is gone. No equity, no asset. Compare that to a mortgage payment (even at an elevated interest rate), and a buyer who can afford the payment is at least building equity in an asset that has historically appreciated. There’s also a secondary effect that often goes unmentioned: in Doussan’s view, higher interest rates tend to soften purchase prices, because fewer buyers can qualify at any given price point. The COVID era showed the inverse: mortgage rates fell to record lows, purchasing power jumped, and prices climbed fast as buyers competed.
Caudill’s complementary point is more operational: the job of an agent in a high-rate environment is to be honest about what a client can actually afford and to keep them out of a house they can’t sustain. His framing from the session was direct: when rates jumped, the conversation was simply that the buyer could afford roughly 20% less, and the agent’s role is to find them the best option in that real range. His goal is a home clients can afford to hold long enough to benefit if values rise; clients who overextend may not get that chance.
If you are talking to a first-time home buyer, they’re paying rent today. Okay, so 100% of that money every month is gone. There’s zero equity in that.
Jeffrey Doussan, Operating Principal, KW New Orleans
Why Doubles Cost Less Per Square Foot Than Single-Family Homes
It’s a question that trips up buyers and even some agents: if a double generates rental income, shouldn’t it be worth more than a comparable single-family home? The answer is counterintuitive and says something interesting about how people actually make purchase decisions.
Doussan’s explanation: investment properties are priced on math. A double (New Orleans shorthand for a two-unit house, often a side-by-side shotgun double) gets valued on its income and its return on investment, so emotion is largely removed from the equation. Single-family homes, by contrast, are priced in a market where buyers routinely pay premiums for things that have no calculable financial return, like the door that lets them watch the dog in the yard while they make breakfast. Those premiums add up, and in Doussan’s view they are why cost per square foot runs higher in the single-family market than in the income-property market.
Doussan applied the same logic to rate increases, pointing to a hotel deal he and Caudill were looking at: when the cost of money goes up, an income property is suddenly worth less, because the price has to come down to keep the return. Single-family pricing, carried partly by emotion, doesn’t run on that math alone. Understanding this distinction helps agents advise clients who are comparing their options across property types in Mid City, Bywater, or anywhere else doubles and singles sit side by side on the same block.
The Downsizing Market Nobody’s Talking About
The housing affordability conversation almost always centers on first-time buyers. Doussan redirected it toward a group that’s been quietly stuck for years.
Older homeowners (the people who bought large family homes decades ago, raised their families in them, and are now ready to sell and move into something smaller) are, in Doussan’s view, the group most constrained by the current rate environment. Some own their homes outright; many others hold low fixed rates locked in years ago, and moving into a smaller home at 2026 rates can mean a new mortgage that doesn’t pencil out compared to staying put. Doussan said that group hasn’t been able to downsize since 2019, and that the downsizing market will stay broken as long as rates stay high.
The downstream effect matters for everyone: when those large family homes don’t come to market, supply stays constrained for the move-up buyers who would have purchased them, which in turn tightens supply for the first-time buyers trying to get into starter homes. The whole inventory chain stalls. Agents working the Garden District, Uptown, and other established neighborhoods full of large older homes feel this acutely.
The real screw here is the older population that wants to sell out of the big family homes that they had that wants to downsize and retire. Those people haven’t been able to downsize since 2019, right? The downsizing market has been broken since COVID.
Jeffrey Doussan, Operating Principal, KW New Orleans
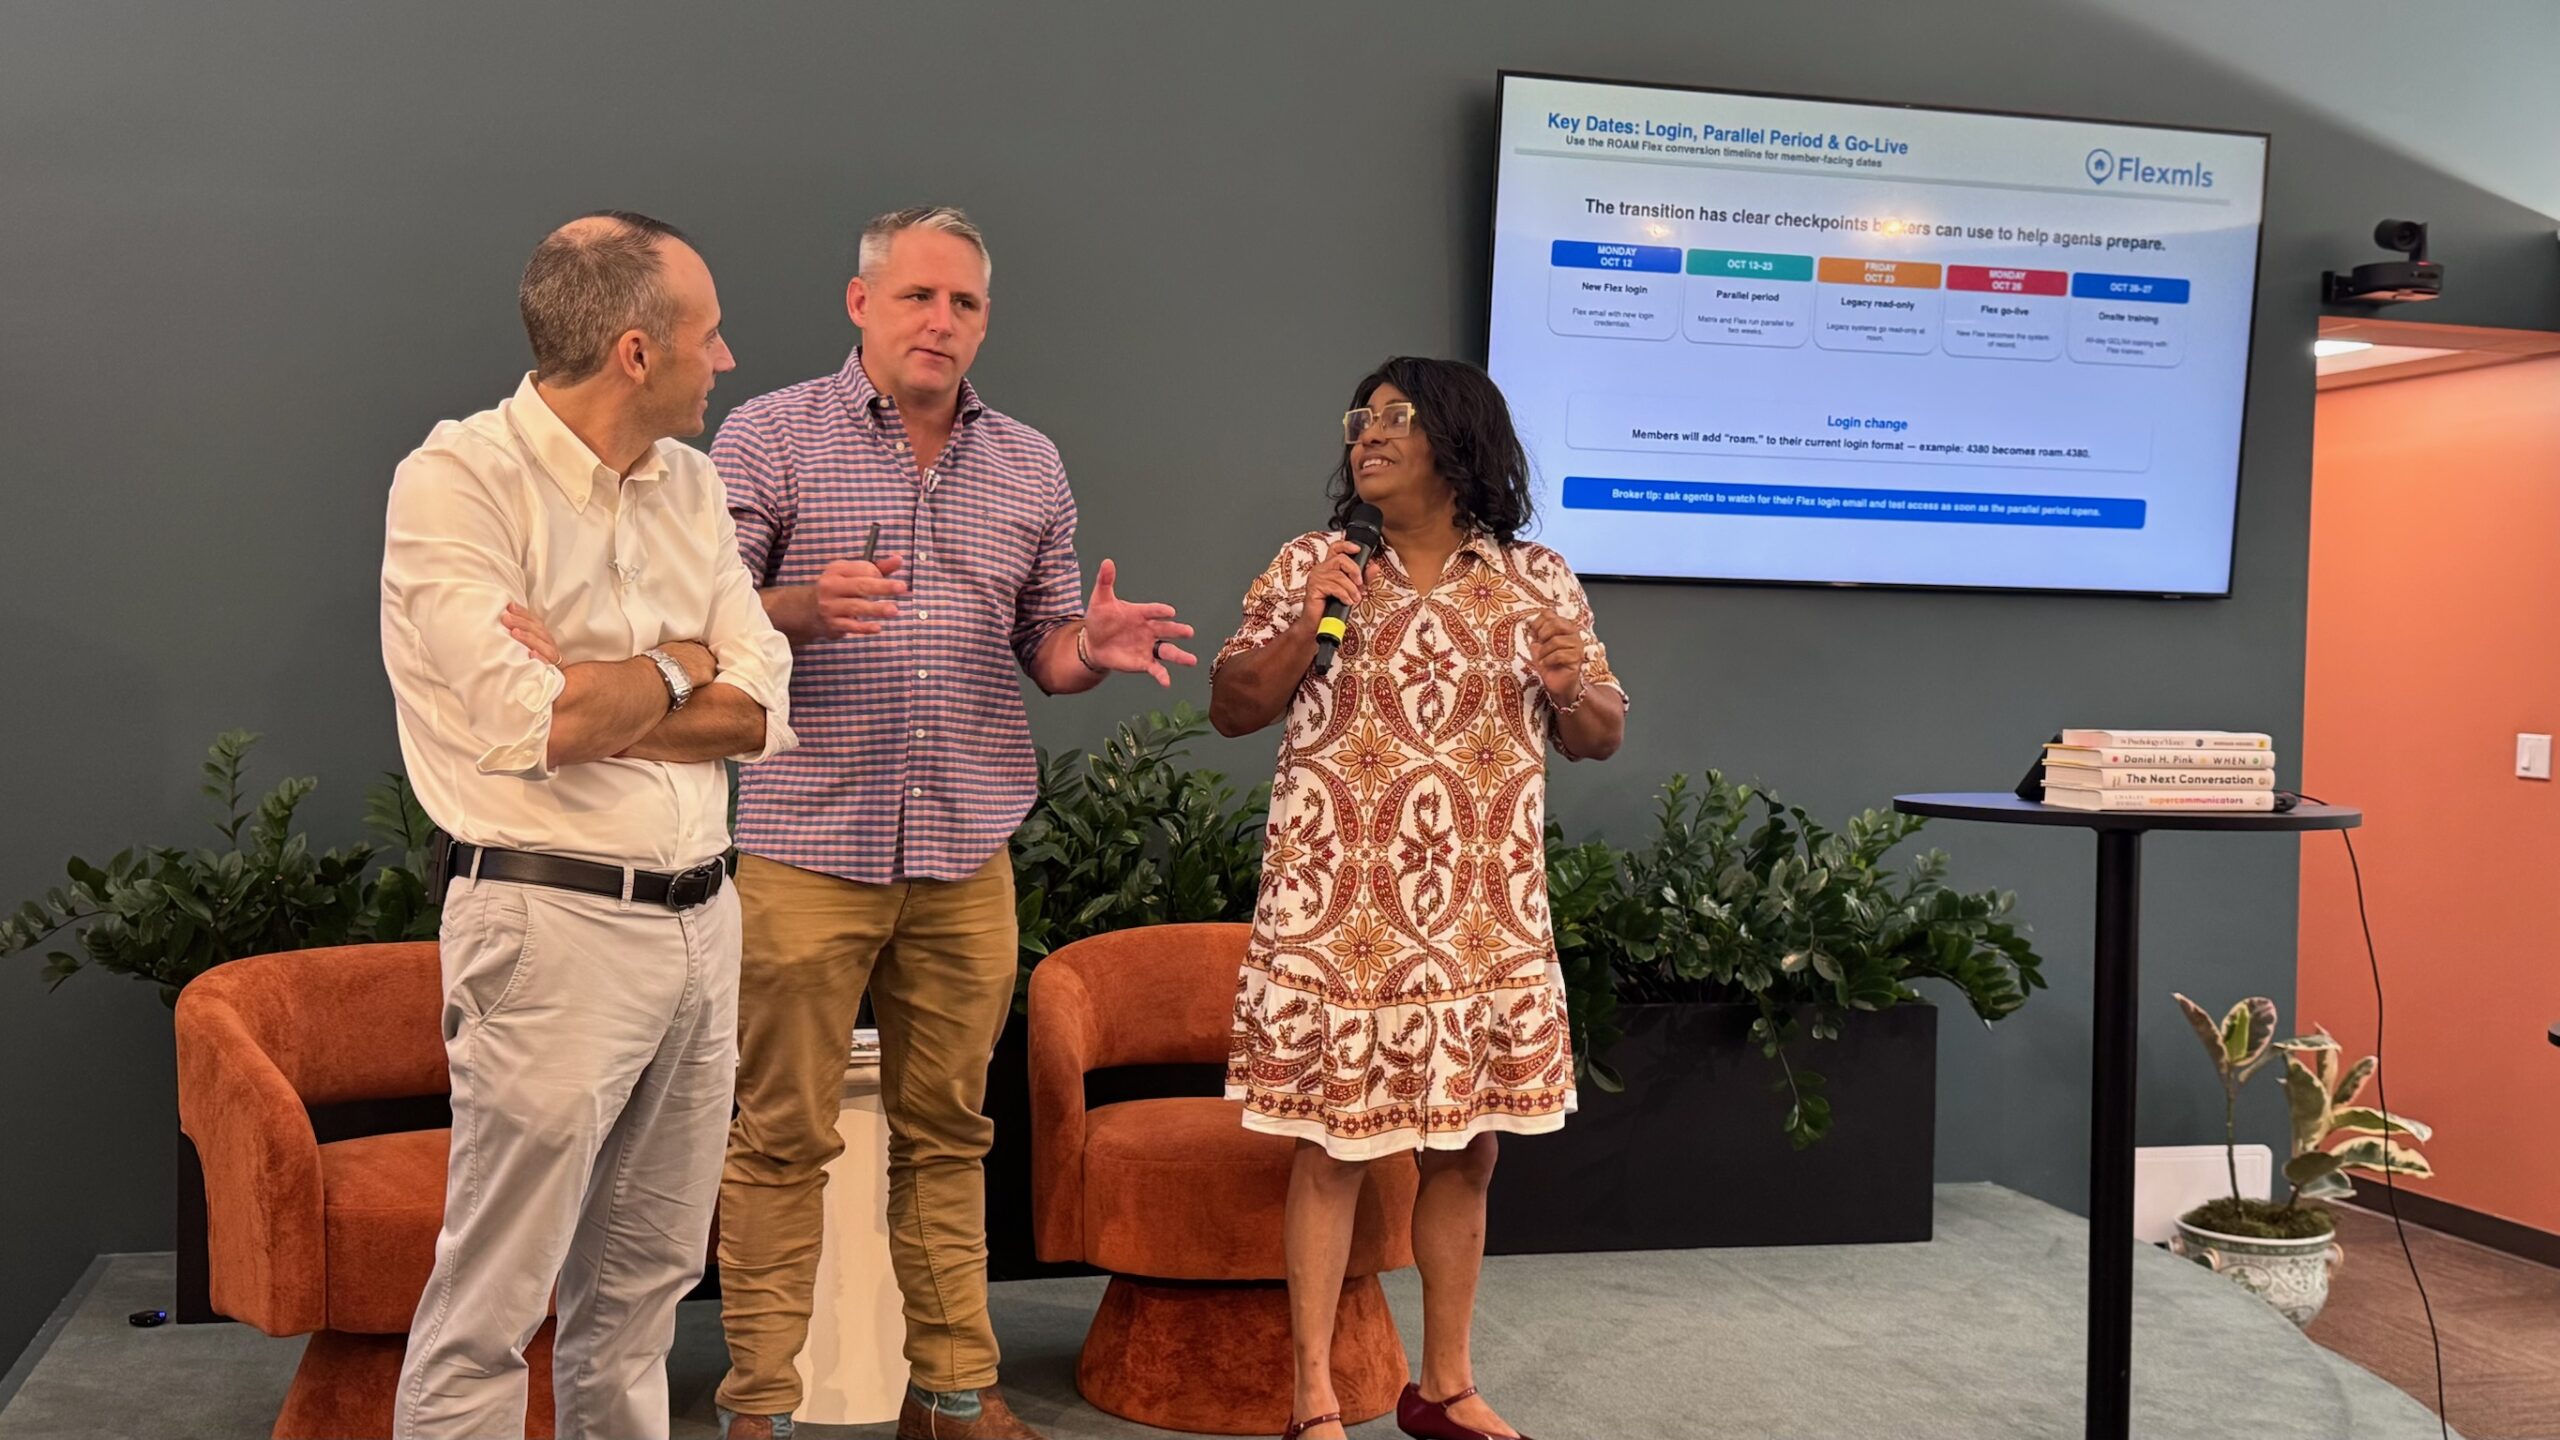
The Matrix-to-Flex Transition: Every Date Agents Need
The MLS platform change isn’t optional, and the timeline is tight. Nichole Donald walked through every critical date, including the one window agents with active listings need to plan around.
New Orleans agents have worked in Matrix, the MLS platform from Cotality (formerly CoreLogic). NOMAR’s MLS is moving to Flex (Flexmls), the platform built by FBS, as ROAM MLS, which combines the MLSs of several Louisiana REALTOR® associations, unifies all of its users on one statewide Flex system. According to Donald, New Orleans is the only ROAM board still on Matrix, while the REALTOR® Association of Acadiana already works in Flex.
Here is the timeline Donald laid out; NOMAR confirmed the key dates in a September 28 member notice:
One practical note Donald emphasized: Flex brings new required fields that Matrix never asked for, especially with a new appraisal system coming in. She held back her partial list on September 16 because it could still change; NOMAR has since named the four new fields agents will see on their first Flex listing: PropertySubType, StructureType, PropertyAttachedYN, and CommonInterest. The appraisal change arriving alongside Flex is the redesigned Fannie Mae and Freddie Mac appraisal report, UAD 3.6, which becomes mandatory for appraisals first submitted on or after November 2, 2026 (lenders with an approved exception may keep using the old format through May 19, 2027); our UAD 3.6 explainer covers what it means for listing agents. Agents entering new listings after October 26 should expect a different data-entry experience and allow extra time for their first few Flex submissions, and the office’s CMA classes in the KW New Orleans learning center are a good place to ask about the new fields.
Common Questions
New Orleans is running its own race. While the national conversation treats high rates as a reason for buyers to wait, KW New Orleans leadership is making the opposite case: rent builds no equity (Doussan says the old line that rent is 100% interest is “almost true”), NOMAR’s average sale price rose nearly 10% in a year, and the agents who help first-time buyers understand that math are the ones actually serving their clients. Meanwhile, the frozen downsizing market (stuck since 2019, in Doussan’s telling) is a big part of why supply stays tight. And starting October 12, every agent in the NOMAR market has a hard operational deadline: learn Flex, verify your contacts and saved searches migrated, and do not have a listing that needs to go active between October 23 and 25. The agents who prepare now get a clean transition; the ones who don’t will find out what a three-day blackout window feels like in the middle of a closing cycle.
About this series. KW New Orleans hosts regular leadership conversations on the forces shaping the New Orleans real estate market, from interest rate dynamics and local pricing trends to the operational shifts every agent needs to stay ahead of. These sessions bring together the people running the office, coaching the agents, and closing the deals.
KW New Orleans brings together sharp, grounded real estate professionals who want to understand the market at a deeper level. If you’re ready to work alongside people who are serious about getting it right, we’d love to talk.