John Ismail, Certified Mortgage Advisor at C2 Financial, on where rates may head through the rest of 2026, what the new UAD 3.6 appraisal report means for your clients, and why he tells ready buyers not to wait.
John Ismail expects mortgage rates to stay higher for longer. Freddie Mac’s weekly survey put the average 30-year fixed rate at 7.28% as of October 1, 2026, up from 7.03% a week earlier. When Ismail spoke on September 30, futures markets were pricing in at least one more Federal Reserve rate hike by December, and he put the gap between the 10-year Treasury yield and 30-year mortgage rates at roughly two and a quarter points, which in his view leaves rates about where they belong. His advice to buyers who can afford the payment and find a home that fits: get under contract instead of waiting on the Fed.
Why It Matters
The New Orleans real estate market has always played by its own rules, but it cannot escape national mortgage rates. According to Ismail, a growing group of borrowers who could barely qualify at 6% cannot qualify at all at 7%, and because New Orleans cannot easily add new houses where buyers want to live, that squeeze lands on the existing housing stock.
John Ismail, a Certified Mortgage Advisor at C2 Financial, joined KW New Orleans Operating Principal Jeffrey Doussan at the brokerage’s weekly team meeting on September 30, 2026. Ismail used to present at that meeting every week before moving to C2 Financial, so the room knew him well. The conversation covered the Fed’s likely next move, rising appraisal costs, a credit score that is opening a second path to approval, and condo reserve rules that could make older buildings harder to finance.
The State of Play
Ismail walked through four forces shaping the mortgage market heading into the final quarter of 2026. In his view, none of them point toward quick relief.
I’ve been in the business now for 21 years, and we were spoiled for about 16 of them as a society, as a country, because the mortgage market was manipulated and rates were kept low for a really long time, and people think it’s normal to get interest rates in the fours, but they’re not. They’re just not.
John Ismail, Certified Mortgage Advisor, C2 Financial
What the Fed’s Next Move Actually Means
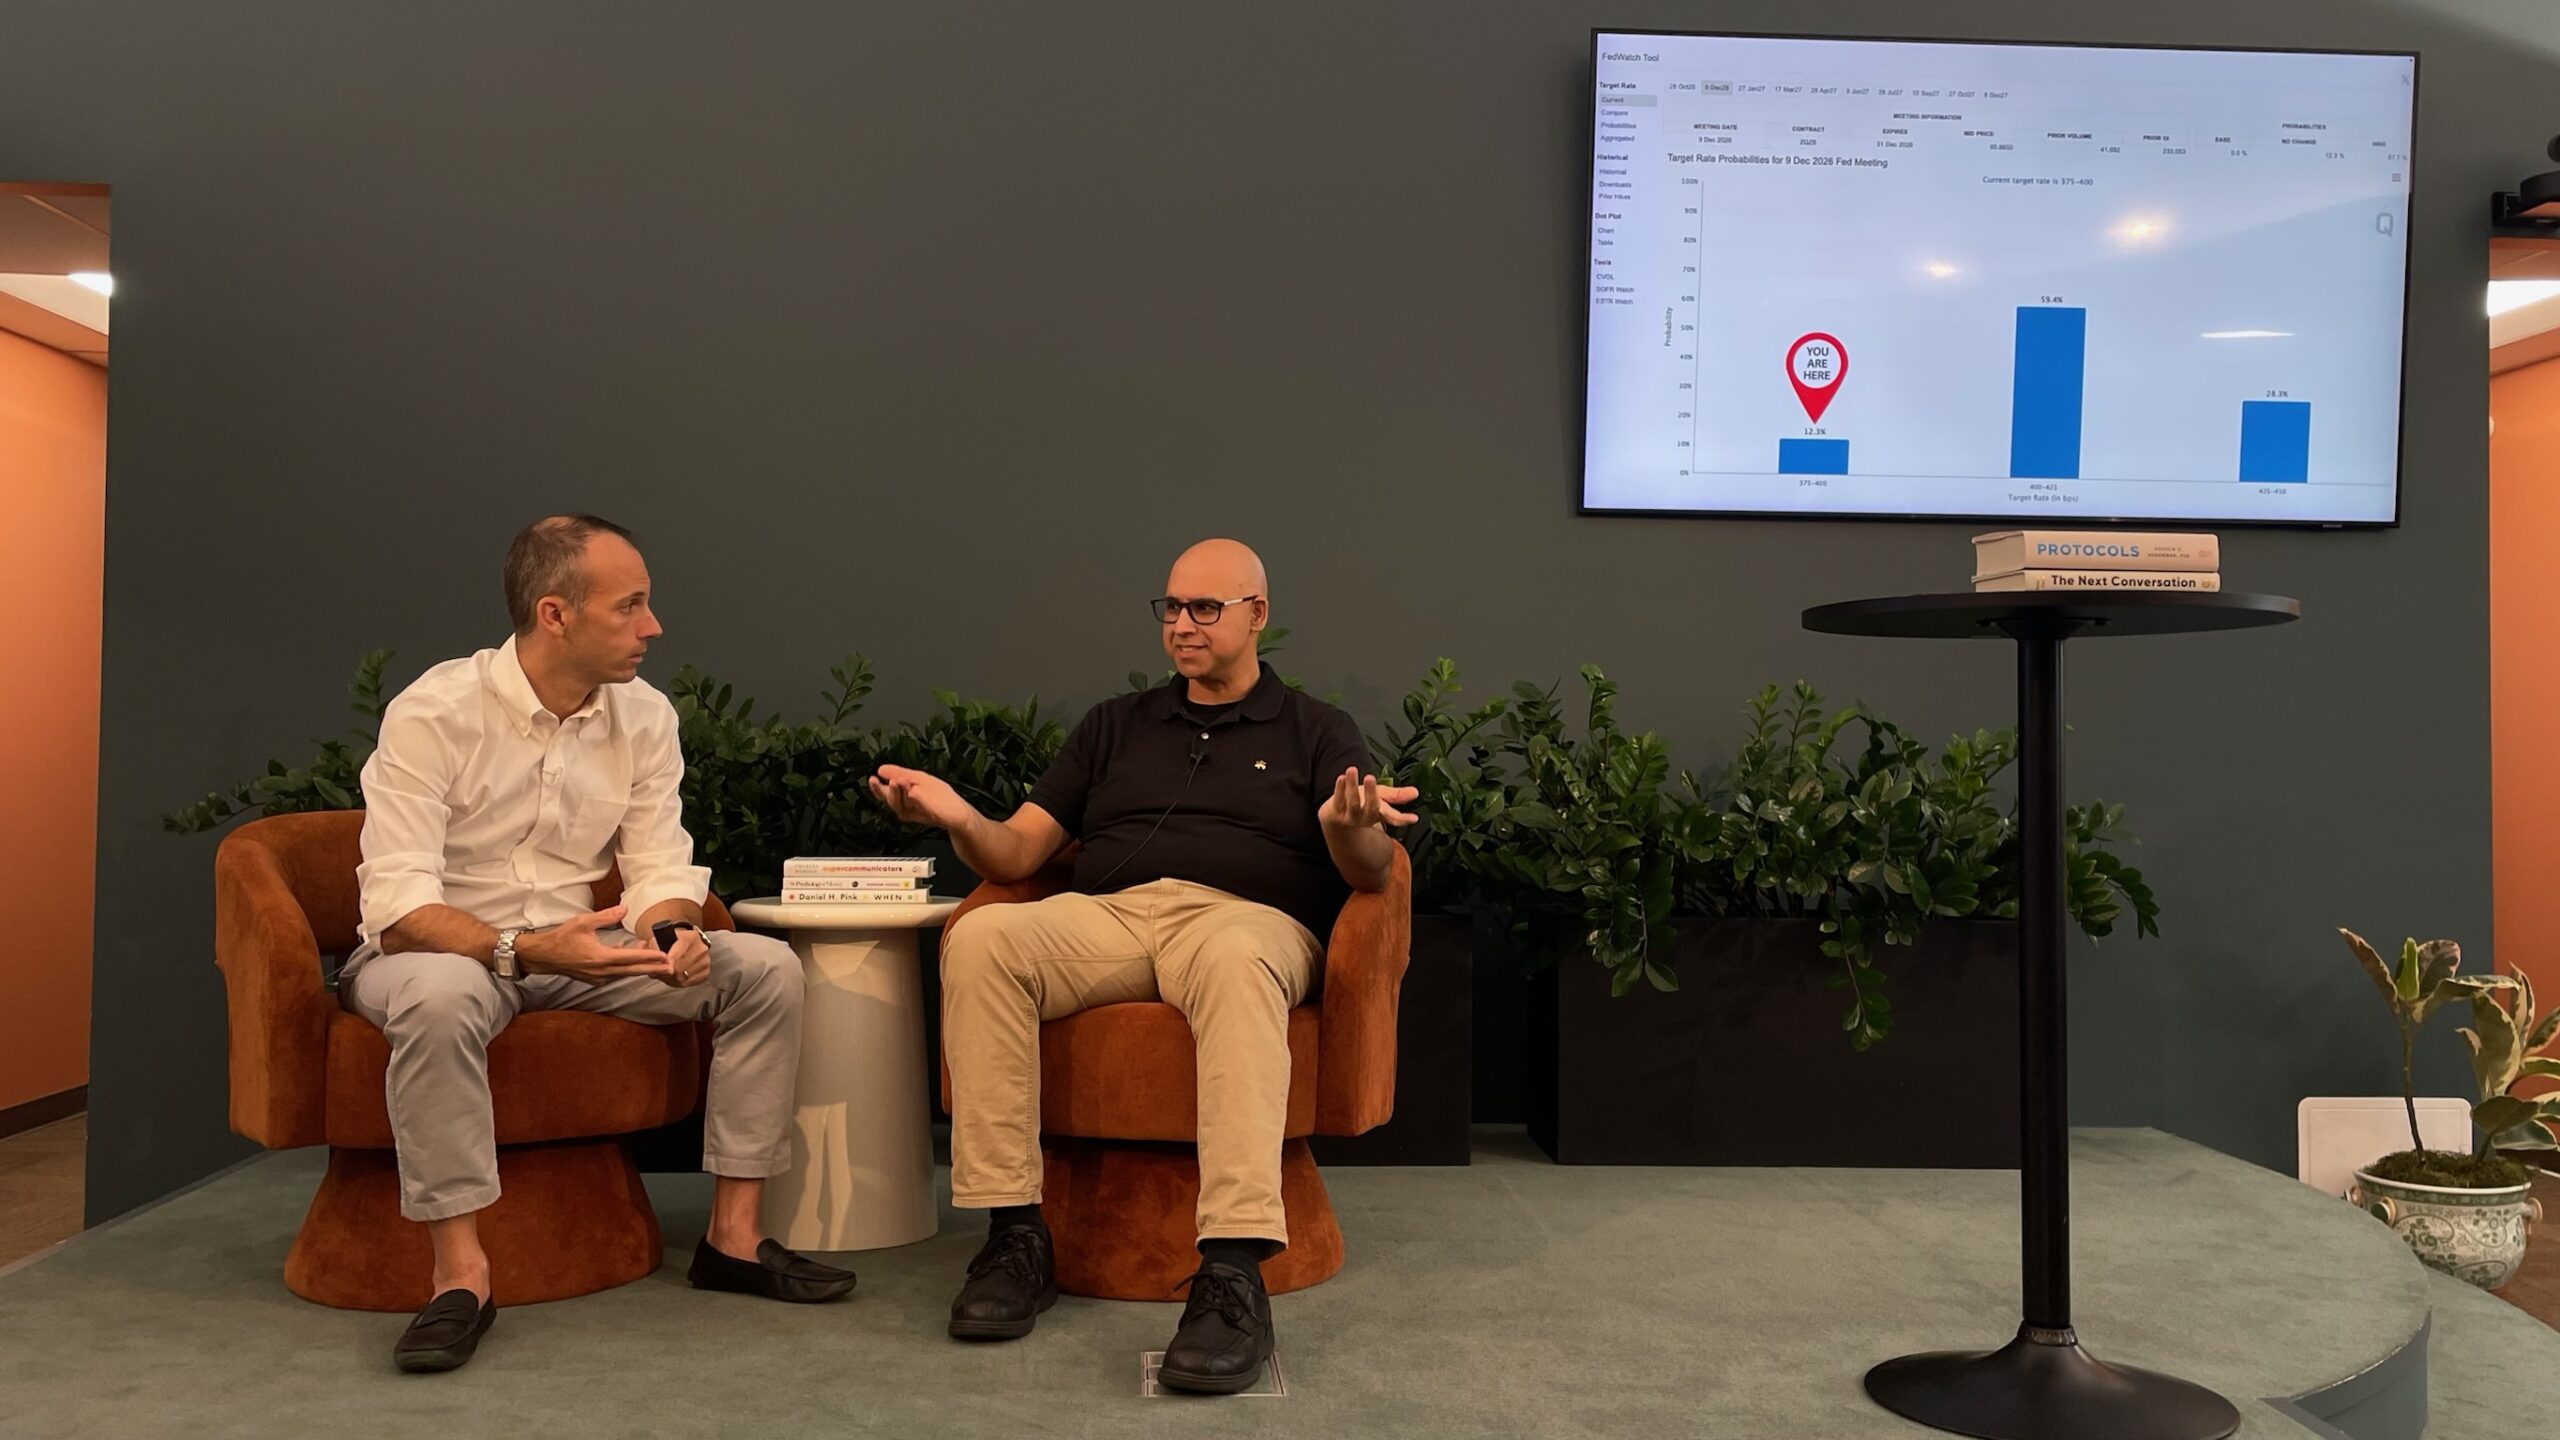
On the CME FedWatch Tool chart Doussan showed on September 30, fed funds futures put the odds of rates being at least 25 basis points higher by the December 9, 2026 Federal Reserve meeting at about 88%, with roughly a 30% chance of a half-point increase by year-end. The Fed had already raised its target range by a quarter point to 3.75% to 4% on September 16. Those odds come from futures trading rather than from the Fed itself, but they show where professional money was positioned.
The practical implication for buyers and agents is timing. Ismail expects that once the October 28 Fed meeting passes without a move, the market will price in December’s expected hike quickly. His read: buyers who are ready should get under contract before that happens. A rate lock holds a quoted rate for the length of the lock period, which limits a buyer’s exposure if rates rise before closing. As Doussan explained, lenders hedge locked loans with options and other trades in the mortgage-backed securities market, which is how a loan officer can quote a rate weeks before closing and still honor it.
Talk in Washington of Freddie Mac buying mortgage-backed securities came up as a possible relief valve, but Ismail was measured about it. With the spread already thin, he estimated the benefit at maybe a tenth of a percentage point, too small to bring buyers off the sidelines.
The Appraisal Cost Problem
Agents are used to clients wincing at a $550 appraisal fee. Ismail and Doussan expect that number to climb toward $800 for a standard single-family home, with pressure coming from two directions at once.
The first is the redesigned appraisal report built on the Uniform Appraisal Dataset (UAD 3.6), which Fannie Mae and Freddie Mac make mandatory for appraisals first submitted on or after November 2, 2026 (lenders approved for a temporary exception can keep using the old format through May 19, 2027). The new report collects far more data than the old one, and in Ismail’s view that data will make machine learning much better at valuing homes down the road. He expects the extra work to add roughly $200 per report. The November 2 mandate covers Fannie Mae and Freddie Mac loans. FHA has said it will move to the same report (FHA INFO 2026-15) and now lets lenders use it, but it has not set a mandatory date, and VA and USDA loans do not require it yet. Our post on Realtor Safety and the New UAD 3.6 Appraisal Report covers the timeline in detail.
The second force is simpler: according to Doussan and Ismail, appraisers have held their fees flat for years and are raising them regardless of the new report. Ismail said he had an $850 appraisal fee disclosed on a non-luxury home the day before the meeting, and it was not a UAD 3.6 report. With the new report and independent fee increases arriving together, the sticker shock could hit clients and sellers harder than either change alone.
For listing agents, the takeaway is concrete. When a buyer asks a seller to cover closing costs, that appraisal line item may no longer be $550; it could be closer to $800. Sellers negotiating concessions should build the higher number into their math before they accept a purchase agreement.
From all the trainings I’ve done on them, I think it’ll be good. The hard part in the beginning is going to be the cost and the time that it takes to get reports back.
John Ismail, Certified Mortgage Advisor, C2 Financial
VantageScore: A Second Path to Approval
Credit reports and the scores attached to them have been essentially unchanged for most of Ismail’s 21-year career. That is starting to shift, and the change is meaningful for first-time buyers in particular.
VantageScore is a credit-scoring model developed as an alternative to the traditional FICO score. On September 4, 2026, the Federal Housing Finance Agency directed Fannie Mae and Freddie Mac to accept VantageScore 4.0 from all lenders. Where FICO has historically rewarded long credit histories and traditional credit products, VantageScore gives weight to rent payments and utility bills when those are reported to the bureaus. That matters for younger buyers who have been paying rent on time for years but have limited credit card or installment-loan history.
According to Ismail, roughly one in four conventional borrowers scores higher under VantageScore than under FICO, usually by 50 to 60 points. He said a gap that size can move a buyer from an FHA loan to a conventional loan, from a higher mortgage-insurance tier to a lower one, or simply into a better interest rate. For some buyers, it is the difference between qualifying and not qualifying.
VantageScore also brings pricing competition to a market where credit reports have become expensive. Doussan compared the two scores to the ACT and the SAT, and Ismail agreed: “One way or another, you can buy a house.” Borrowers get a second path to approval, and lenders get price pressure on data costs. Ismail added that trended credit data, which shows the direction of a borrower’s credit behavior over time rather than a single snapshot, is coming next year.
Condo Reserve Rules: The Building Matters Now
Condo financing has always depended on the building as well as the buyer, and Fannie Mae’s building-level rules are getting stricter.
Under Fannie Mae’s Lender Letter LL-2026-03, condo projects that go through a full project review must budget at least 15% of their annual assessment income for reserves, up from 10%, for loan applications dated on or after January 4, 2027. Ismail flagged the change at the meeting. An association collecting $100,000 a year in condo fees would need to budget at least $15,000 of it for reserves. The same letter lets projects with ten or fewer units qualify for a waiver of project review (five- to ten-unit projects cannot be part of a master association or larger development), which is relevant in New Orleans, where many “condo” properties are effectively shared-wall homes with small owner groups. For what a full review looks at, see Condo Due Diligence Just Got Harder.
The bigger exposure is in older buildings. Ismail said the rule of thumb he has been given is 30 years: buildings that age or older tend to carry deferred maintenance, and associations that have underfunded reserves may face a choice between special assessments on unit owners and losing eligibility for conventional financing. In a city where Doussan joked that anything under 30 years counts as “new construction,” plenty of buildings sit on the wrong side of that line. Newer condo developments, Ismail said, have no trouble meeting the requirement.
Rate Buydowns: The Negotiating Tool That Fits This Market
With the average 30-year fixed rate at 7.28% as of October 1, according to Freddie Mac, sellers who want to move their property have a lever that costs them money at closing but can help hold together deals that would otherwise fall apart on affordability.
A temporary interest rate buydown is a concession, often paid by the seller, that lowers the buyer’s rate for the first one to three years of the loan before it steps up to the note rate. Ismail called the 1-0 buydown (one year at one point below the note rate) and the 2-1 buydown (two points below the note rate in year one, one point below in year two) the most useful structures. He prefers short-term buydowns over permanent ones in this environment, because in his experience a permanent buydown is usually not financially feasible unless it lowers the rate by more than a quarter to three-eighths of a point.
His reasoning is practical: the first year of homeownership is the most expensive, particularly for first-time buyers absorbing move-in costs, furnishings, and repairs. A lower payment in that first year is cash that matters when it arrives. His advice to buyers’ agents is to try to negotiate short-term buydowns into purchase agreements now rather than wait for sellers to offer them.
Always for as long as I’ve been alive, if you can afford it and the house fits your need, yes, contract immediately.
John Ismail, Certified Mortgage Advisor, C2 Financial
Common Questions
John Ismail’s message in September 2026 was not complicated, but it ran against the instinct of buyers and sellers holding out for a better moment. In his view, rates in the sevens are roughly where they belong given the historical relationship between the 10-year Treasury and the 30-year mortgage, and the long run of rates in the fours was the anomaly. Nobody can promise where rates go next. Meanwhile, three changes are reshaping deals right now: appraisal fees could climb toward $800 for a standard home, older condo buildings with thin reserves risk losing eligibility for conventional financing as Fannie Mae’s reserve rules tighten, and VantageScore is opening a second path for buyers who would have been turned away under FICO alone. Agents who understand all three, and who negotiate temporary buydowns into purchase agreements, are the ones putting deals together while everyone else waits for a rate that may not come.
About this series. KW New Orleans hosts regular conversations with the leaders shaping our city: developers, architects, investors, and operators building the New Orleans of tomorrow. These are the conversations that happen in the rooms most people don’t get invited into.
KW New Orleans brings together the sharpest minds in real estate, finance, and development. If you’re ready to work alongside people building the city’s future, we’d love to talk.